Every time the Federal Reserve meets, one question seems to come up around Tahoe: Are mortgage rates about to change?
Maybe. But not necessarily in the way people expect.
A Fed announcement can move financial markets. It doesn't directly set the 30-year mortgage rate your lender offers, and a quarter-point move by the Fed doesn't automatically create the same quarter-point change on a mortgage quote.
That distinction is especially important right now, when financing can make the difference between a comfortable Tahoe purchase and a monthly payment that feels like a stretch.
Start with a rate that's on the record
Freddie Mac reported a 7.24% national average for a 30-year fixed-rate mortgage as of October 29, 2026, down from 7.32% the week before and the lowest weekly average this month. The 15-year fixed averaged 6.60%, down from 6.68%. A year earlier, the 30-year survey average was 6.17%. Freddie Mac's survey represents a specific conventional, conforming, well-qualified borrower profile. It is not a live quote for every borrower, loan amount, vacation home, condominium, or jumbo purchase in Tahoe.
That last part matters. Two Tahoe buyers can look at the same house and receive meaningfully different rate and fee options based on credit, occupancy, down payment, property type, loan size, and the lender's pricing.
One number on a national survey is a useful benchmark. It isn't a substitute for a current written loan estimate that fits the actual purchase.
Rate math, in real dollars
Take a hypothetical $600,000 loan, fixed for 30 years, principal and interest only:
At 6.17%, the payment is approximately $3,663 per month.
At 7.24%, the payment is approximately $4,089 per month.
That's approximately $426 more each month on the same loan amount.
These figures are calculated examples, not available loan offers. They exclude property taxes, insurance, HOA dues, mortgage insurance if applicable, utilities, and closing costs. Rate, APR, points, and loan terms are different things; compare the full package, not just the headline percentage.
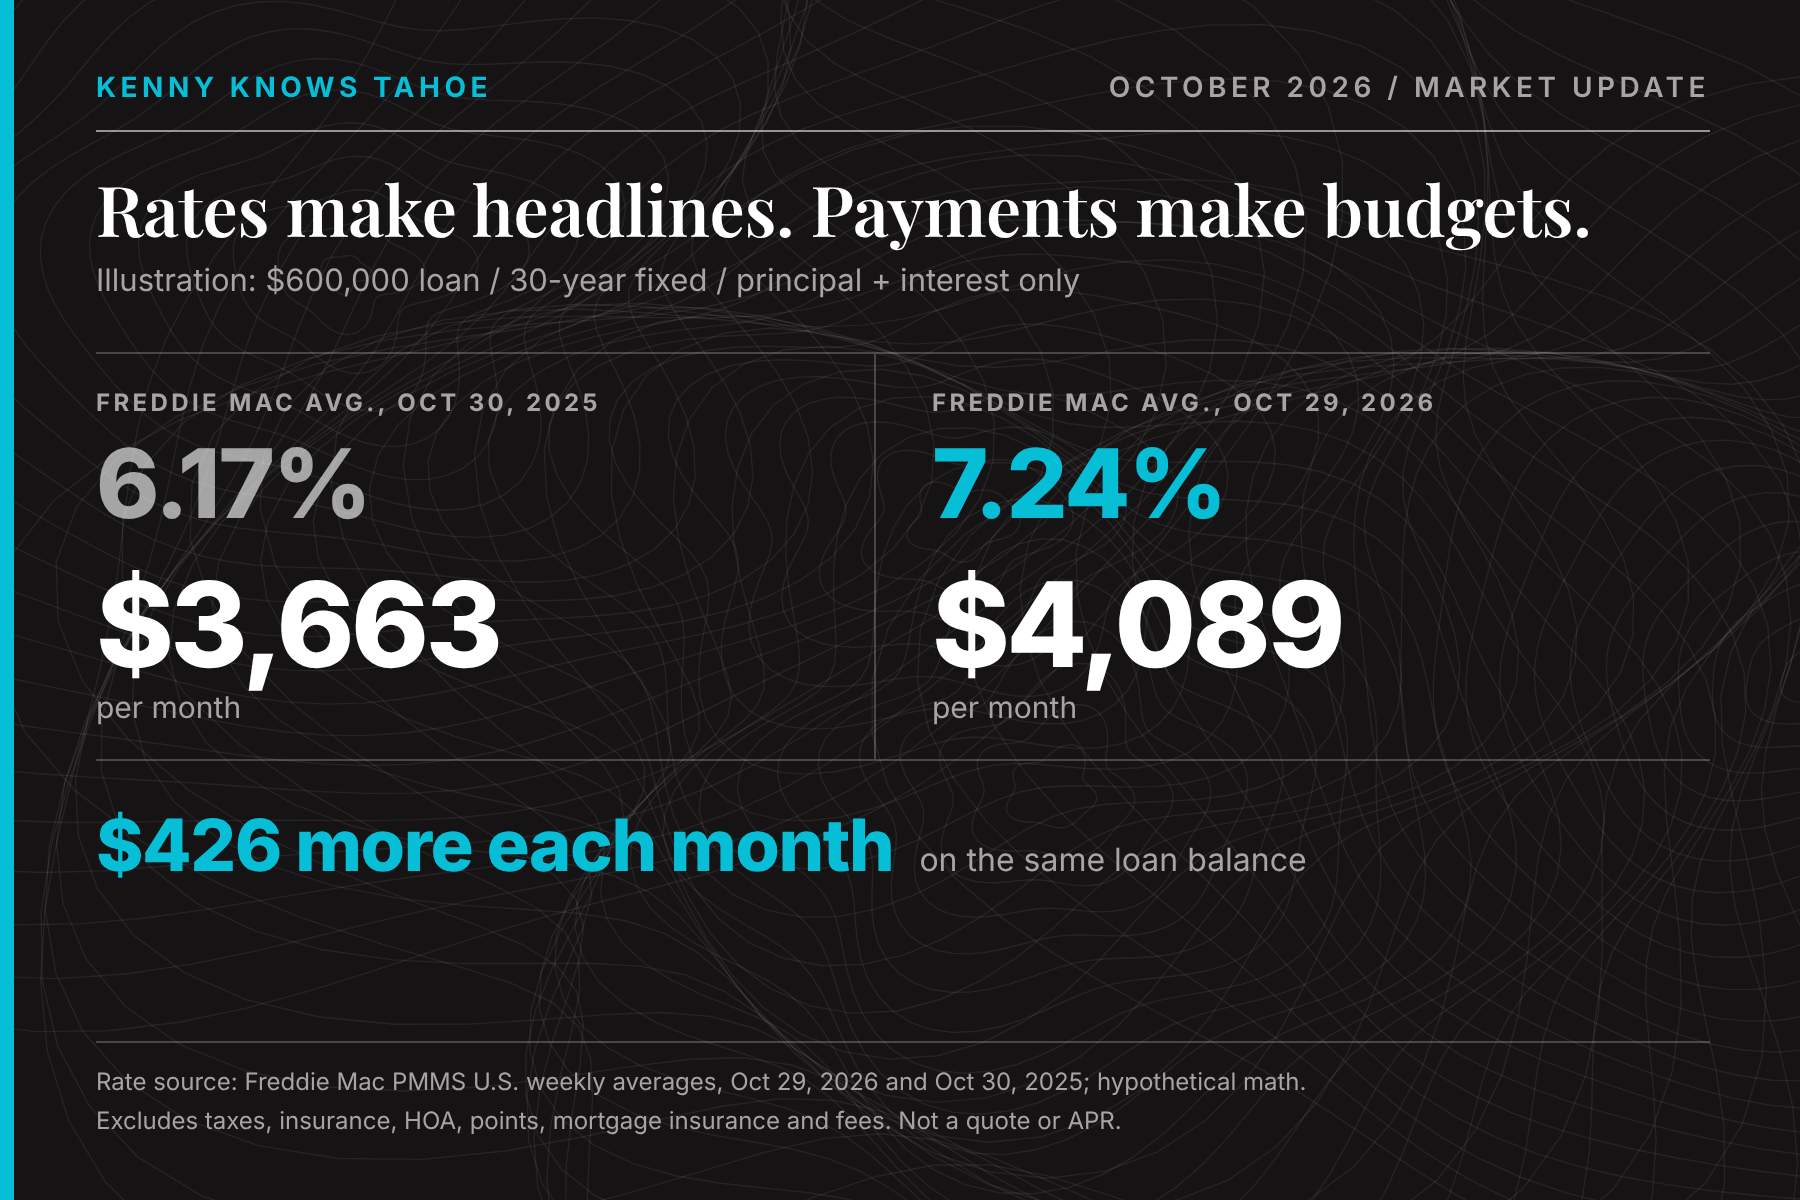
Hypothetical principal and interest only. Rates from the Freddie Mac Primary Mortgage Market Survey, October 29, 2026, and October 30, 2025.
The payment gap is real. So is the need to keep it in perspective. A buyer with a smaller loan, a different rate lock, or another financing structure will have different numbers. And a lower payment isn't automatically the best overall deal if getting that rate requires paying excessive upfront fees.
Why the Fed and the bond market both get a vote
The Fed controls a short-term benchmark interest-rate target. Fixed mortgage rates are influenced more directly by the market for longer-term bonds and mortgage-backed securities, along with lender spreads and risk factors.
Inflation is one reason those bonds have been moving around. On October 14, the Bureau of Labor Statistics reported that September consumer prices rose 3.7% over 12 months. The report also showed a 0.6% monthly increase, with higher gasoline prices accounting for more than half of that monthly increase.
Higher-than-expected inflation can put upward pressure on longer-term yields, but markets also respond to what investors had already anticipated, economic growth, Treasury issuance, and demand for bonds. Mortgage rates can shift even before the Fed releases a statement.
The Fed's October 28 decision was a hold at 3.75% to 4.00%, the range it set with a quarter-point increase in September. The vote was 10 to 2, and both dissenting members preferred another quarter-point increase.
The statement described economic activity as expanding at a strong pace and inflation as elevated. That kind of language, along with incoming inflation data, can move longer-term bond yields, and through them, mortgage pricing. Even then, the rate a Tahoe buyer is actually quoted still depends on the loan, the property, the borrower, and the lender.
Skip the crystal ball, check the payment
First, know the payment at a realistic present-day quote. Then make sure the rest of ownership fits: taxes, HOA costs if any, utilities, winter upkeep, and a property-specific insurance estimate.
Second, ask your lender to explain the actual cost and break-even point of discount points, a temporary buydown, an adjustable-rate loan if appropriate, or a different down-payment structure. Those can be useful options, but they're not interchangeable. Terms, eligibility, risks, and approval matter.
Third, decide whether the home itself makes sense at the price and payment you can qualify for today. Refinancing could be an option in the future, but it depends on market conditions, qualifications, value, and costs. It isn't something to rely on to make an otherwise uncomfortable purchase work.
Wrapping It Up
The mortgage market gives us plenty to watch, especially around a Fed meeting. The best decision doesn't require guessing the next move perfectly. It requires understanding what today's numbers mean for your property and budget.
And in Tahoe, that conversation should always include the cost of owning the home after you've got the keys, including winter costs like snow removal.
Kenny Rutledge
Broker Associate at COMPASS Realty
CA & NV Tahoe Specialist
Direct line: (530) 906-3880
Kenny@KennyKnowsTahoe.com
KennyKnowsTahoe.com
Sources: Freddie Mac Primary Mortgage Market Survey, October 29, 2026, and October 30, 2025; U.S. Bureau of Labor Statistics September 2026 CPI release, October 14; Federal Reserve FOMC statements of September 16 and October 28, 2026. Rate and Fed details updated October 30, 2026. Freddie Mac's survey average is not a specific lender offer; payment examples are principal and interest only. Ask a licensed mortgage professional about qualification, loan estimates, fees and financing options. CA DRE #02053147 and NV RED #S.0205700.